Student-Loan Offsets Renew Social Security Policy Fight
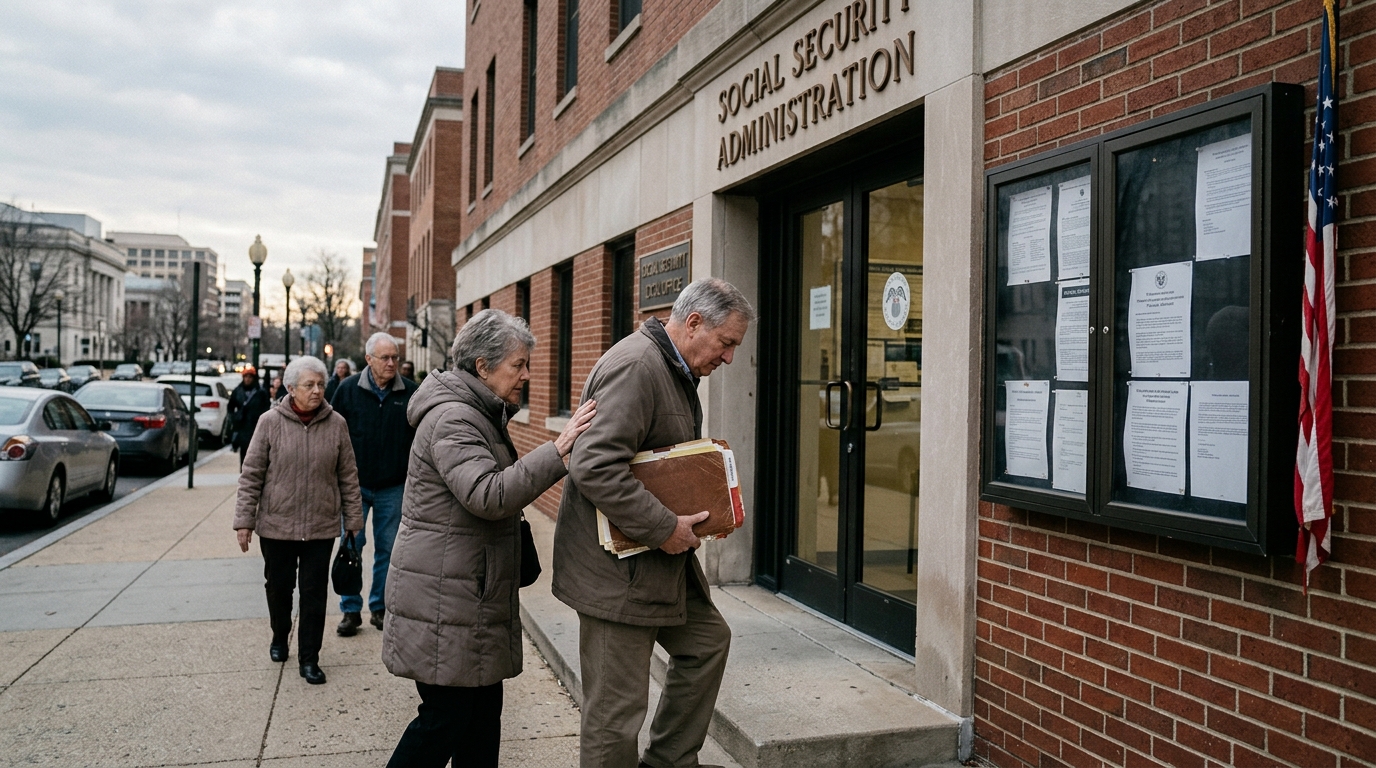
A U.S. policy debate with direct household and market implications is back in focus after MarketWatch reported that the government can take 15% of Social Security benefits to repay student loans, while new proposals seek to stop the practice.
The issue sits at the intersection of retirement income, consumer finances and federal debt collection policy. Although it is primarily a domestic policy story, it matters for markets because it touches disposable income for older Americans and highlights the continuing political sensitivity around student debt and benefit protections.
Why this policy question matters now
According to MarketWatch, current rules allow the government to offset a portion of Social Security benefits to recover student-loan debt. Proposals now aim to block that. The debate is significant because it blends two politically sensitive areas: support for retirees and the government’s approach to collecting outstanding education debt.
For households, the effect is straightforward. Any reduction in monthly Social Security income can pressure spending flexibility, particularly for retirees with limited room in their budgets. For policymakers, the issue raises a broader question of whether debt-collection tools designed to recover federal funds should apply in the same way to older beneficiaries.
That makes this more than a personal-finance headline. It is also a signal about how Washington may balance fiscal recovery efforts with income protection for vulnerable groups.
Consumer and economic read-through
While MarketWatch focused on the proposals themselves, the wider economic relevance comes from household cash flow. Social Security benefits play a central role in supporting consumption for many older Americans. If policy changes reduce the likelihood of benefit offsets, that could help preserve spending power for affected households. If the current framework remains in place, the burden would continue to fall on borrowers whose retirement income is already constrained.
For markets, this fits into a larger pattern: policy changes that affect fixed-income households can influence consumer behavior at the margin, especially in categories tied to essentials. The impact is unlikely to be broad enough on its own to alter macro forecasts, but it contributes to the wider picture of how fiscal policy interacts with household resilience.
It also underscores that the student-debt debate is no longer limited to younger borrowers or recent graduates. The persistence of education debt into retirement has become a policy problem with a different social and economic profile.
The political dimension
Any attempt to stop Social Security offsets would likely attract attention across party lines because it touches retirement security, fairness and federal budget discipline. Supporters of change can argue that retirement benefits should be protected from debt collection. Opponents may frame the issue around repayment accountability and the precedent set by limiting recovery tools.
MarketWatch reported that proposals are seeking to stop the offsets, but the path forward will depend on whether those proposals gain enough traction in Washington. That leaves room for continued uncertainty, especially as student-loan policy remains one of the more contested areas of federal economic governance.
The market relevance is therefore less about immediate pricing and more about policy direction. Investors following consumer demand, retirement themes or fiscal debates may view the story as part of a broader shift in how the U.S. government handles household debt stress.
A broader signal on retirement vulnerability
The renewed focus on Social Security offsets also reflects a larger concern: financial vulnerability among older Americans. Retirement income policy has become more closely tied to issues that were once treated separately, including education debt, healthcare costs and inflation pressure on fixed budgets.
That context helps explain why this issue can resonate beyond personal finance readers. It is a reminder that the structure of household balance sheets can carry policy consequences long after the original borrowing decisions were made.
What to watch next
- Legislative traction: whether proposals to end offsets advance beyond the discussion stage
- Policy framing: whether the debate centers on retiree protection or debt recovery
- Household impact: how the issue feeds into wider concerns over retirement income security
Neutral outlook: The Social Security offset debate is unlikely to move markets on its own, but it is a meaningful policy signal on retirement security, household cash flow and the future direction of student-debt enforcement.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.