Inflation Keeps Fed Tightening Bias in Focus
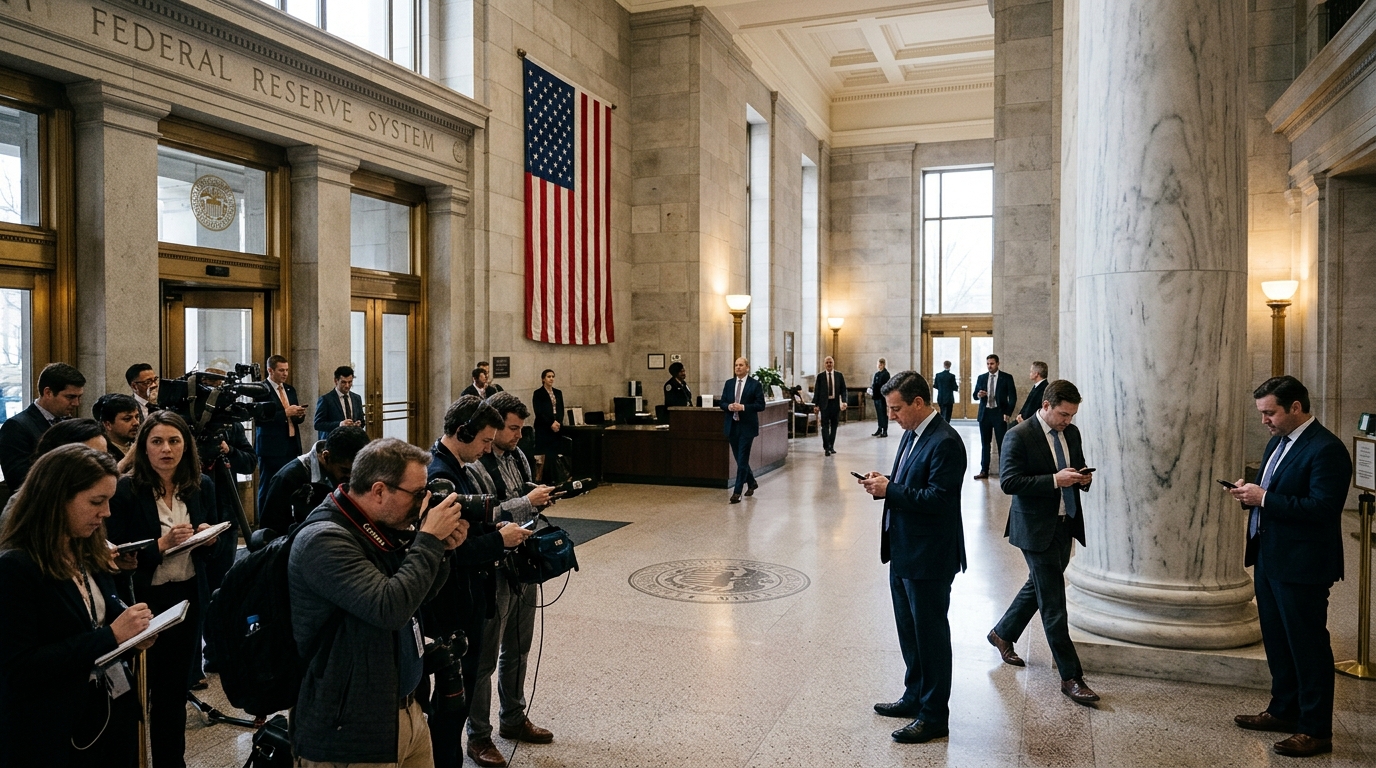
U.S. inflation and Federal Reserve policy expectations returned to the center of market attention after fresh reports indicated price pressures remain firm enough to keep a tightening bias in play. MarketWatch reported that hot U.S. inflation has not cooled off and said rising consumer prices are likely to keep the Fed on its rate-hike track, while Investing.com, citing Russell Investments, reported that the Fed is “going to have little patience with inflation.”
For global markets, that combination matters most in foreign exchange and broader risk sentiment. When inflation remains sticky and the central bank is seen as unwilling to ease up, investors typically reassess how long U.S. rates may stay elevated. That can support the dollar, pressure rate-sensitive assets and complicate the outlook for equities and commodities that have recently benefited from hopes of easier monetary conditions.
Why inflation headlines still move currency markets
The inflation story is not just about consumer prices in isolation. It is also about the policy reaction function. If incoming price data suggest inflation is proving difficult to bring down, markets may conclude the Fed has less room to turn dovish. According to MarketWatch, the latest inflation backdrop does not support the idea that price growth has decisively cooled. Investing.com separately highlighted commentary that the Fed may show limited tolerance for renewed inflation pressure.
That is especially important for the dollar because U.S. rates remain the anchor for global capital flows. Higher-for-longer expectations can make dollar assets relatively more attractive, particularly against currencies where central banks are closer to ending tightening cycles or where domestic growth is weaker.
For multinational companies and global investors, a firmer dollar can also affect earnings translations, import costs and funding conditions. In that sense, inflation is not just a domestic macro data point; it is a cross-asset driver that can spill into equities, bonds, commodities and crypto markets.
Fed path remains the key transmission channel
The latest reporting reinforces that markets are still highly sensitive to any sign the Fed could keep pressure on financial conditions. If inflation fails to moderate convincingly, policymakers may decide that restrictive settings need to be maintained for longer than investors had expected earlier in the cycle.
That possibility matters because recent market positioning in several asset classes has reflected some hope that disinflation would gradually open the door to a more stable rates backdrop. A setback to that view can trigger rapid repricing. In currency markets, that often shows up first in the dollar. In equities, it tends to hit sectors with long-duration valuations. In fixed income, it can lift Treasury yields or at least reduce confidence in a near-term easing path.
Neither MarketWatch nor Investing.com suggested an immediate policy decision beyond emphasizing that inflation remains a live concern. But taken together, the reports underline a simple point: the market’s rate narrative is still vulnerable to upside inflation surprises.
What global investors are likely watching next
The immediate market question is whether inflation persistence becomes a one-off concern or a more durable pattern. Investors will likely keep focus on:
- Upcoming inflation releases, for evidence of whether price pressures are broadening or easing.
- Fed communication, especially any shift in tone around tolerance for sticky inflation.
- Dollar performance, as a real-time gauge of whether rate expectations are tightening again.
- Risk assets, including equities and crypto, for signs that higher-rate worries are spilling over.
The broader significance is that inflation remains the market’s most important macro variable because it shapes policy, and policy shapes global liquidity. That helps explain why even a modest shift in inflation expectations can have an outsized effect on currencies and wider asset pricing.
Neutral outlook: According to MarketWatch and Investing.com, inflation has not softened enough to take Fed tightening risk off the table. Markets are likely to stay data-dependent, with the dollar and broader risk appetite remaining especially sensitive to the next inflation signals.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.